Roof Damage Insurance Claim Guide for Tennessee
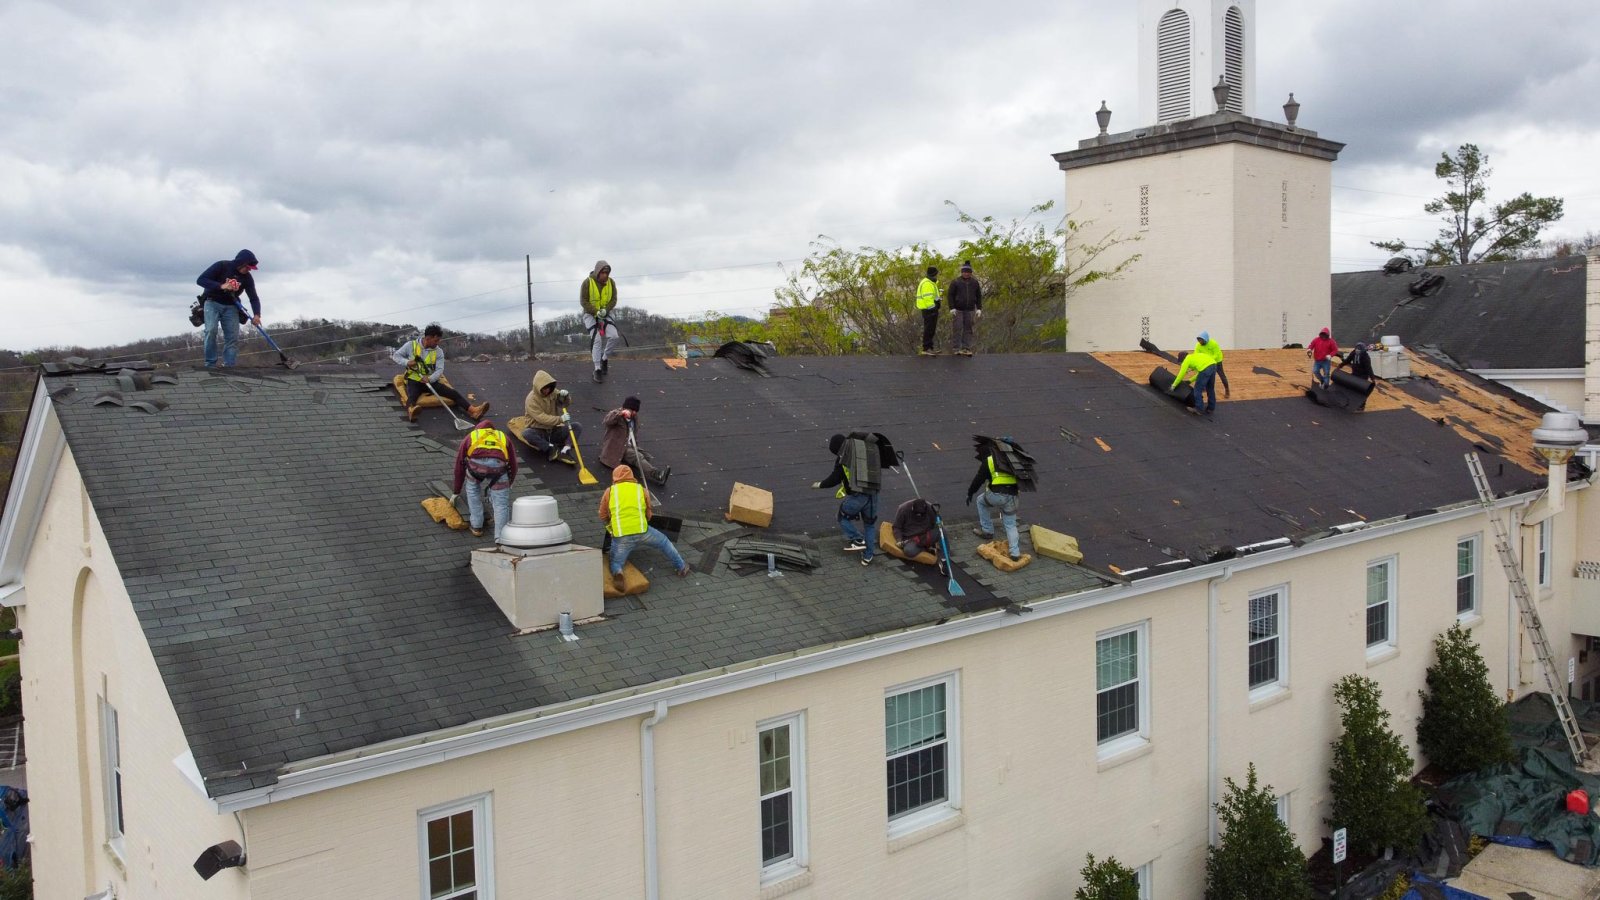
Imagine walking out to your driveway in Gallatin or Hendersonville after a severe Middle Tennessee thunderstorm and finding shingles scattered across your lawn. It's a frustrating moment that leaves many homeowners feeling uncertain about what comes next. You likely worry about whether your insurance will cover the repairs or if you'll be stuck with a high deductible and a leaking roof. Dealing with property damage is inherently stressful, and the fear of a denied claim only adds to that burden. Most homeowners feel overwhelmed when they first start the roof damage insurance claim process, wondering how to prove the extent of the damage to their carrier.
Ultimate Solution Roofing & Exteriors is here to provide the clarity you need. In this guide, you'll learn the exact steps to document damage, file a claim, and restore your property using professional local expertise. We'll explain how Tennessee's matching regulations protect your home's appearance and why professional documentation is often more influential than an adjuster's initial assessment. Our team brings 20 years of experience to every inspection, helping property owners throughout Greater Nashville manage every step from the first shingle lost to the final repair. We'll provide a clear roadmap for your restoration, ensuring you have the evidence required to return your roof to its pre-storm condition.
Key Takeaways
- Learn how to safely assess storm damage from the ground and prioritize structural integrity before contacting your insurance carrier.
- Understand the step-by-step roof damage insurance claim process, including how to review your specific policy details and filing deadlines.
- Discover why having an experienced contractor from Ultimate Solution Roofing & Exteriors present during the adjuster's inspection ensures all damage is documented for your Greater Nashville home.
- Identify common missing line items in insurance summaries, such as code upgrades and the Tennessee regulation regarding shingle matching.
- Gain a clear roadmap for scheduling your restoration and selecting high-quality materials to return your Middle Tennessee property to its pre-storm condition.
Immediate Steps Following a Storm in Middle Tennessee
Middle Tennessee experiences intense weather patterns, particularly during the peak spring and fall storm seasons. Severe wind gusts and large hail are common occurrences in areas like Gallatin and Portland, often leaving behind damage that isn't immediately obvious. When a storm passes, your first priority is safety. It's vital to document the date and time of the event immediately, as your homeowners insurance policy often has strict contractual windows for reporting a loss. Starting the roof damage insurance claim process with accurate records helps establish a clear timeline for your carrier and avoids confusion later in the project.
Ensuring Personal Safety First
Before checking for property damage, look for immediate hazards around your home. Stay away from downed power lines or trees that appear to be leaning precariously toward your structure. Storm damage can sometimes compromise the structural integrity of a building, making it dangerous to enter certain areas. Avoid the temptation to climb onto your roof to look for leaks or missing shingles. Ultimate Solution Roofing & Exteriors emphasizes that professional equipment and training are necessary for any roof-level inspection to prevent falls or further damage. Instead, watch for interior signs of trouble, such as yellowing ceiling stains or active drips in the attic, which indicate immediate water intrusion.
Documenting Visible Exterior Damage
You can gather significant evidence from the safety of the ground. Use your phone to take wide-angle photos of your entire property to show the context of the storm's impact. These images help adjusters understand the severity of the weather event. Look for "bruising" on shingles, which often appears as dark, circular spots where hail has knocked off protective granules. Check these specific areas for supporting evidence:
- Gutters and downspouts: Look for fresh dents or heavy granule buildup in the discharge areas.
- Siding and window screens: Identify holes, tears, or cracks caused by wind-blown debris or hail.
- Roofing materials: Note any shingles that have lifted, creased, or scattered across the lawn.
- Yard debris: Document large tree limbs or pieces of metal flashing that have been displaced.
While ground-level signs are helpful, they don't tell the whole story. Hail damage is often invisible to the untrained eye but can lead to premature roof failure years later. Contacting a professional for a storm damage inspection is the most reliable way to verify the condition of your home. Ultimate Solution provides detailed photographs and professional estimates that serve as the foundation for your claim. We serve homeowners throughout Middle Tennessee, including Lebanon and White House, ensuring your property is evaluated by local experts who understand our regional weather patterns and building requirements.
Filing Your Roof Damage Insurance Claim
Once you have identified storm impact on your property in Nashville or Hendersonville, the next step in the roof damage insurance claim process is officially notifying your carrier. This begins by locating your "Declarations Page," which provides a summary of your limits and deductibles. The Tennessee Department of Commerce & Insurance recommends filing as soon as possible to ensure you meet policy deadlines. While Tennessee law provides a three-year statute of limitations for property damage, many individual policies contractually limit your filing window to one year from the date of the storm. Notifying your agent early helps you receive a claim number, which acts as the tracking ID for every document and inspection moving forward.
Understanding Your Policy Coverage
Before you call, it's helpful to know how your specific policy handles depreciation. Most homeowners in Middle Tennessee have either Actual Cash Value (ACV) or Replacement Cost Value (RCV) coverage. An ACV policy pays out the current value of the roof based on its age, while an RCV policy is designed to pay the cost of a full replacement at current market rates. You should also identify your deductible. This is the portion of the repair cost you are responsible for paying. Tennessee law (Tenn. Code Ann. Section 62-6-604) forbids contractors from paying or rebating your deductible, so you should be wary of any company that suggests they can handle the cost for you. Having these details ready ensures a more productive conversation with your insurance representative.
The Role of Professional Estimates
Ultimate Solution Roofing & Exteriors provides a comprehensive professional estimate that serves as a vital piece of evidence for your carrier. Our team uses 20 years of experience to identify damage that an insurance adjuster might overlook during a brief visit. A high-quality estimate isn't just a total price; it's a detailed list of every component required to restore your home. We document related exterior damage to gutters, siding, and window screens to ensure the full scope of the storm's impact is recognized.
A detailed estimate from our team includes:
- High-resolution photographs of shingle bruising and wind uplift.
- Itemized lists of materials, including flashings and underlayment.
- Documentation of local building code requirements for Gallatin or White House.
- Evidence of material discontinued status to support Tennessee's matching regulations.
By providing this level of detail, Ultimate Solution helps you present a complete picture of the loss to your insurance company. If you need assistance documenting the condition of your roof before you call your agent, you can request a professional inspection from our local team. This proactive approach ensures your claim is based on professional data rather than a quick visual check.
The Insurance Adjuster Inspection and Meeting
After you receive a claim number from your carrier, the next significant phase in the roof damage insurance claim process is the field inspection. Your insurance company will assign an adjuster to visit your property in Lebanon, Gallatin, or Portland to verify the loss. This meeting is a pivotal moment, as the adjuster's report forms the basis for your settlement offer. While the adjuster works for the insurance company, Ultimate Solution Roofing & Exteriors can be present to provide a professional perspective on the physical condition of your roof. Our team acts as a knowledgeable guide, ensuring that every area of concern we found during our initial assessment is clearly pointed out.
Why Professional Representation Matters
Adjusters often have heavy schedules, especially following a major Middle Tennessee storm. Having our team on-site allows us to provide the adjuster with the detailed photographs and measurements we've already gathered. We focus on technical accuracy, such as verifying the total "squares" of the roof and identifying specific building code requirements for your local municipality. This collaborative approach helps prevent discrepancies in the initial scope of work.
It's important to understand the legal boundaries during this meeting. Under Tennessee law (TCA § 56-6-1001), a roofing contractor cannot negotiate a claim or settlement amounts on your behalf unless they hold a public adjuster license. Ultimate Solution operates strictly within our professional lane. We document the damage, provide comprehensive estimates, and coordinate the technical details of the restoration. We provide the carrier with the facts they need to make an informed decision, though the final approval remains with your insurance company.
Identifying Storm-Specific Damage Markers
During the inspection, the adjuster will look for specific evidence that the damage was caused by a covered peril rather than normal wear and tear. Our team helps identify these markers to ensure a thorough review:
- Hail Impact Patterns: We look for "bruising" or dark, circular spots where hail has knocked off protective granules. We also check "soft metals" like attic vents, gutters, and chimney flashing for dents, which serve as collateral evidence of hail size.
- Wind-Related Failures: High winds in areas like Hendersonville can break the adhesive seal of asphalt shingles. We document unsealed tabs and horizontal creases that indicate the shingle was lifted and folded back during the storm.
- Structural Vulnerabilities: We examine high-slope areas and ridges where wind speeds are highest. If your roof is older, we help the adjuster understand how its age and material condition contributed to the failure of the roofing system.
By having Ultimate Solution Roofing & Exteriors present during the inspection, you can feel confident that the damage is properly documented. This professional support helps the adjuster see the full extent of the storm's impact on your property before they leave the site.
Reviewing the Claim Summary and Scope of Work
After the field inspection is complete, your insurance carrier will provide a document known as a claim summary or scope of work. This paperwork is the itemized blueprint for your restoration, detailing every repair the adjuster has approved. It's common for homeowners in Middle Tennessee to feel overwhelmed by these multi-page reports, which use industry-specific software like Xactimate. The most critical step in the roof damage insurance claim process is comparing this summary against the professional estimate provided by Ultimate Solution Roofing & Exteriors. If there are discrepancies in the measurements or missing line items for essential components like flashing or ridge vents, these must be addressed before construction begins.
Decoding ACV vs. RCV Payments
Most insurance settlements are paid in two stages. The first check you receive is typically for the Actual Cash Value (ACV), which represents the current value of your roof after accounting for depreciation based on its age. Once the work is finished and our team submits a final invoice, the carrier releases the remaining funds, known as the Replacement Cost Value (RCV), to cover the full cost of the restoration. It's important to remember that your deductible is a fixed out-of-pocket cost and is your responsibility as the property owner. Under Tennessee law (Tenn. Code Ann. Section 62-6-604), a residential roofing contractor cannot demand payment until your insurer has confirmed coverage, ensuring you aren't paying for repairs that haven't been approved.
The Supplement Process for Missing Items
Adjusters sometimes omit necessary items required by local building codes in Gallatin, Hendersonville, or Nashville. For example, modern codes may require the installation of a drip edge or specific underlayment that wasn't present on your original roof. Additionally, Tennessee regulation 0780-01-05-.10(1)(b) requires insurers to provide a "reasonably uniform appearance." If your existing shingles are discontinued and a match cannot be found, the carrier may need to supplement the claim to cover a full replacement rather than a mismatched patch.
Ultimate Solution provides the detailed documentation, including ITEL material reports and photographs of code violations, to support these necessary supplements. We work to ensure the carrier has all the technical facts required to update the scope of work so your home is restored correctly. This process ensures that no essential safety or structural components are left out of the final project plan.
By carefully reviewing the scope of work with our team, you can identify these gaps early. This proactive approach prevents unexpected costs during the build and ensures your new roofing system meets all current Tennessee safety standards and manufacturer specifications.
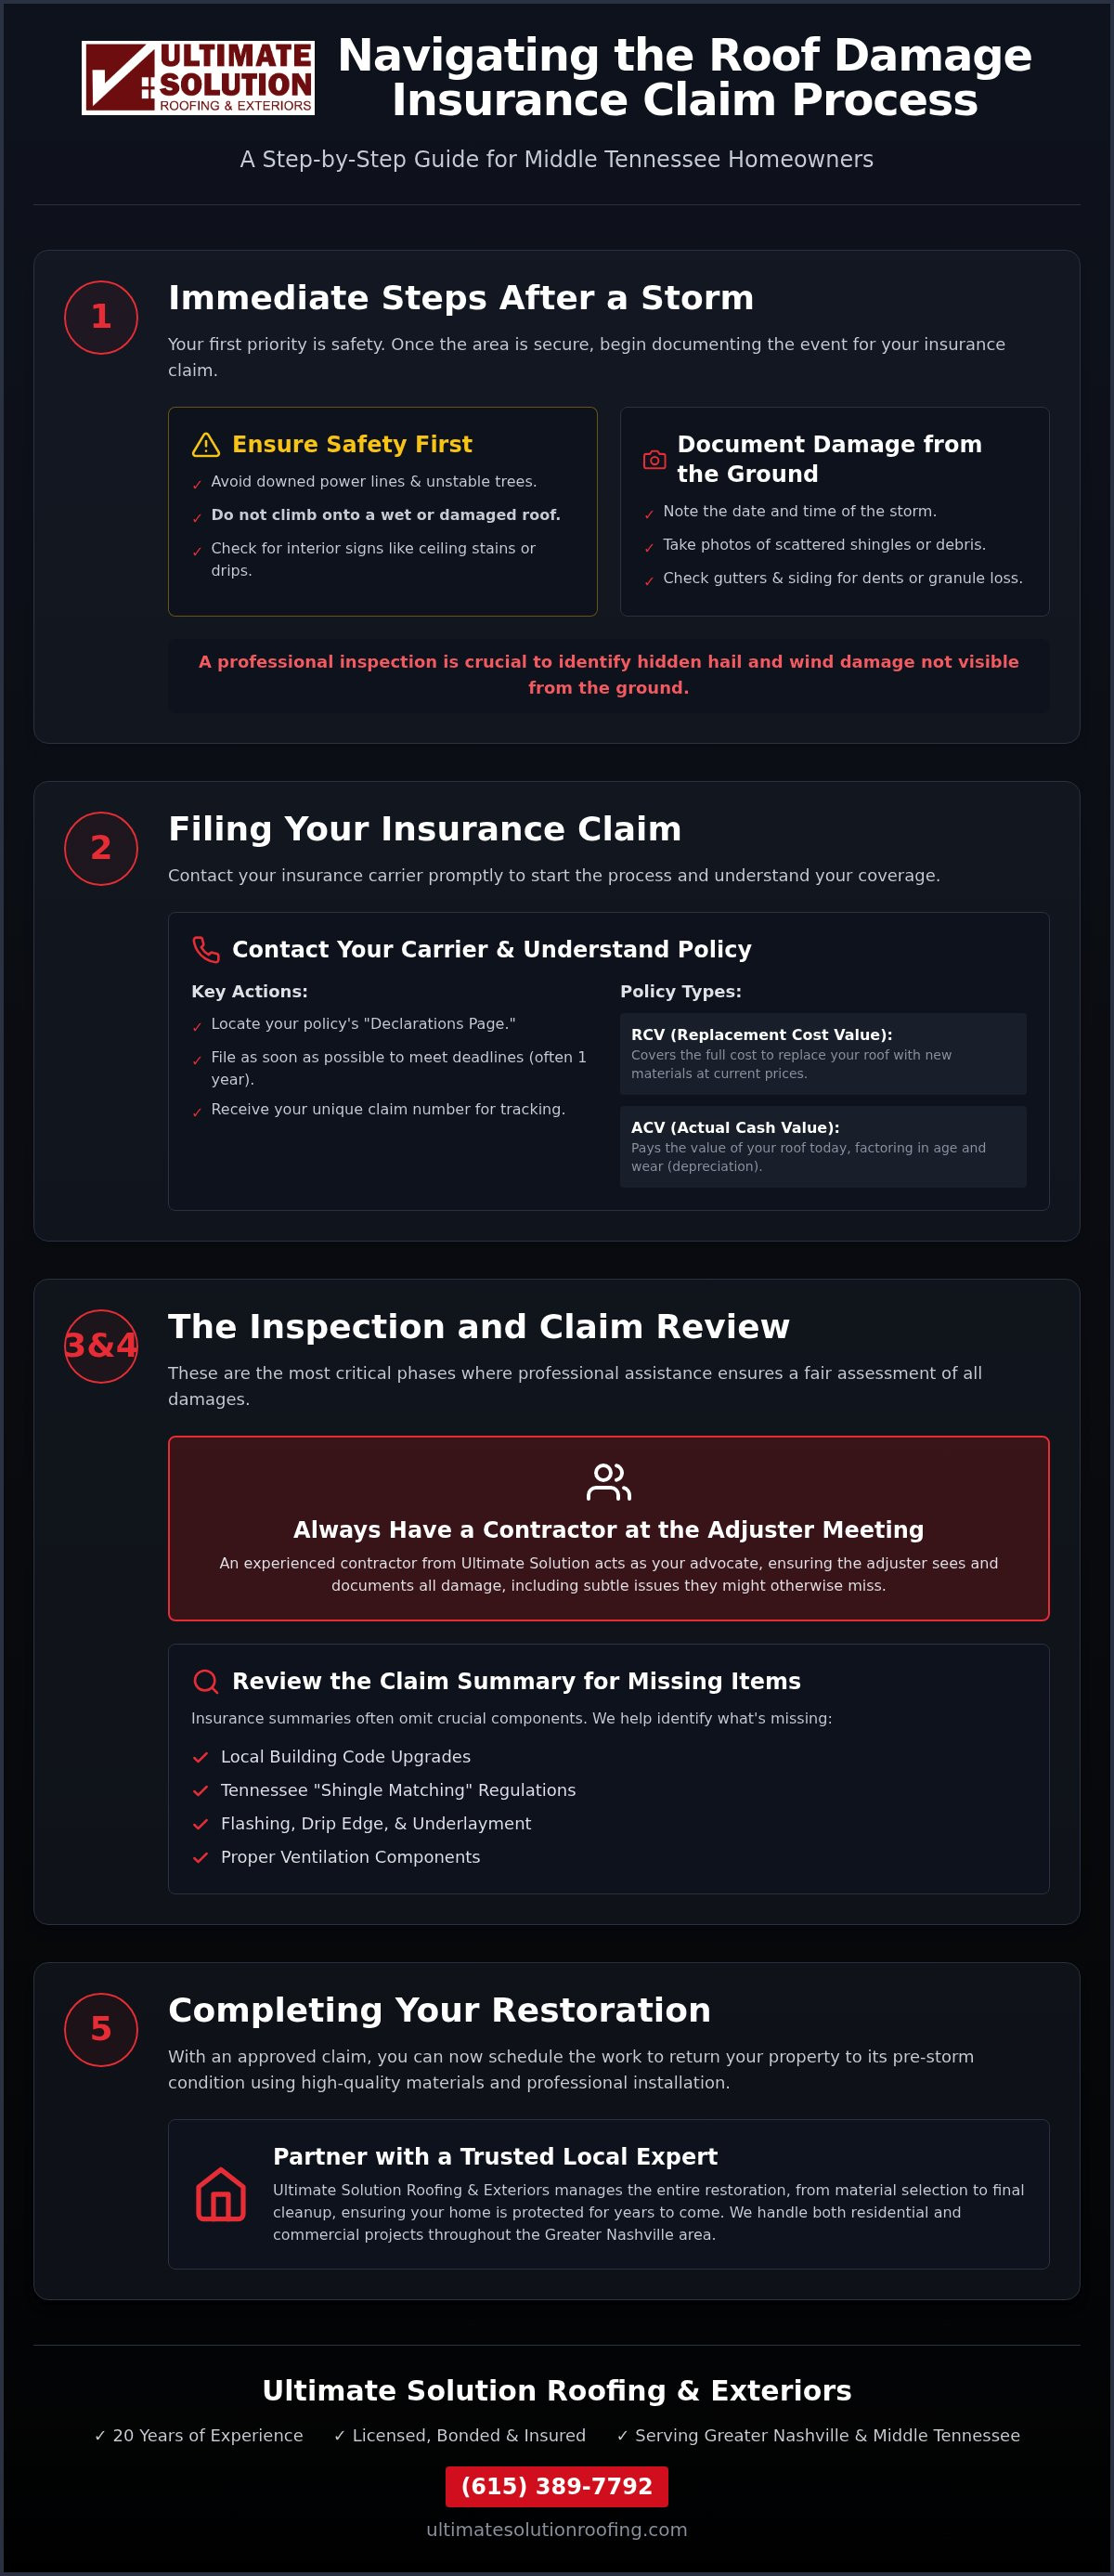
Completing Your Restoration with Ultimate Solution
Once the technical details of the roof damage insurance claim process are resolved, the focus shifts to the physical restoration of your property. This stage is where your documentation efforts pay off, transitioning from paperwork to professional craftsmanship. Ultimate Solution Roofing & Exteriors approaches every build with a focus on long-term durability, ensuring your home is prepared for future Middle Tennessee weather patterns. We schedule our projects to minimize disruption to your daily routine, maintaining a clean and organized job site from start to finish. Our goal is to provide a seamless transition from a damaged structure to a fully restored roofing system.
Professional Installation and Quality Care
Selecting high-quality materials is essential for a roof that lasts. Our team provides expert guidance on asphalt shingles, metal roofing, and specialty materials that perform best in the high-wind and hail-prone environments of Gallatin, Portland, and Hendersonville. We use our 20 years of experience to ensure every component, from heavy-duty underlayment to ridge vents, is installed to manufacturer specifications. You can learn more about our residential roofing services to see how we handle both standard repairs and full replacements throughout the Greater Nashville area. We focus on choosing materials that withstand the thermal expansion common in Tennessee's climate.
Finalizing the Insurance Paperwork
Completing the physical roof is only part of the project. To receive your final payment, we must submit a Certificate of Completion and a final invoice to your insurance carrier. This documentation notifies the company that the work is finished, allowing them to release the recoverable depreciation, or RCV funds, that were held back from the initial check. According to current Tennessee insurance standards as of September 2026, homeowners typically have one year from the claim approval date to complete these repairs and claim their depreciation. Our team coordinates this documentation to ensure your file is updated promptly.
It's common for insurance checks to include your mortgage company as a co-payee. This requires an additional step of sending the check to your lender for endorsement, a process our team helps you manage by providing the necessary project documentation they require. Once all funds are released, we perform a final walk-through with you to ensure every detail meets your expectations. Our team ensures your property is thoroughly cleaned, with a focus on removing all construction debris and nails from your landscaping. Your home is restored to its pre-storm condition, providing the security you expect from a professional installation. If you're ready to begin your restoration or need a professional assessment of your storm damage, contact our team at (615) 389-7792 to start the process with a local partner you can trust.
Restore Your Property with Expert Local Support
Successful restoration after a storm requires more than just a quick repair. It involves a structured approach that prioritizes safety and thorough evidence. By following a clear roadmap, you can manage the roof damage insurance claim process with confidence. It's essential to document damage immediately from the ground and ensure a professional is present during the insurance adjuster's visit to verify the technical details of the loss. Ultimate Solution Roofing & Exteriors brings 20 years of experience to every project, providing the detailed photo documentation required to support your claim for residential and commercial properties throughout Middle Tennessee.
As a family owned and locally owned business, we understand the specific building codes and weather patterns in Gallatin, Hendersonville, and White House. Our team is dedicated to providing high-quality craftsmanship that returns your home to its pre-storm condition. We focus on transparency and reliability, ensuring you feel supported from the initial inspection to the final certificate of completion.
We look forward to helping you restore your property with the professional care it deserves.
Frequently Asked Questions
How long do I have to file a roof damage insurance claim in Tennessee?
Most policies in Middle Tennessee require you to file within one year of the date of loss, which is the day the storm occurred. While Tennessee state law allows up to three years for property damage lawsuits, your insurance contract often shortens this window significantly. Filing early is the best way to ensure you meet all contractual obligations and secure the evidence needed for the roof damage insurance claim process before deadlines expire.
What happens if my insurance claim is denied but I have visible damage?
You have the right to request a re-inspection if you believe the adjuster missed significant damage. Ultimate Solution Roofing & Exteriors can provide detailed photo documentation and a professional estimate to present as new evidence to your carrier. Sometimes a different adjuster or a supervisor is assigned to review the file. Providing clear, technical proof of storm-specific markers like hail bruising or wind uplift helps clarify the situation for your insurance company.
Will my insurance rates go up if I file a claim for storm damage?
Insurance companies generally don't raise your individual rates solely because of a single weather-related claim, as storms are considered "Acts of God." However, if a major storm affects a large portion of a city like Nashville or Lebanon, the carrier might adjust premiums for an entire zip code based on the increased risk. You should consult your specific policy or agent for details on how regional claims history affects your long-term premium costs.
Should I get a roof repair or a full replacement after a storm?
The choice between repair and replacement depends on factors like the age of your roof, the extent of the damage, and the condition of the materials. If the damage is localized and the roof is relatively new, a repair might be sufficient. However, if the storm compromised a large area or the shingles are discontinued, a full replacement is often necessary to ensure a uniform appearance and meet Tennessee's matching regulations for a consistent look.
Do I need to get multiple estimates for my insurance company?
You aren't legally required to provide multiple estimates to your insurance carrier in Tennessee. You have the right to choose a local contractor you trust to perform the work. While some adjusters might suggest getting several quotes, it's more important to find a team with 20 years of experience that provides an itemized scope of work. This ensures the estimate accurately reflects the actual costs of materials and current local building codes in your area.
What is a deductible, and who is responsible for paying it?
A deductible is the specific amount you agreed to pay out-of-pocket before your insurance coverage begins. If your roof replacement costs $15,000 and your deductible is $1,000, the insurance company will issue payments totaling $14,000. As the property owner, you are responsible for paying that $1,000 directly to your contractor. This amount is typically subtracted from the first check you receive during the roof damage insurance claim process for your restoration.
Can a roofing company pay my insurance deductible for me?
No, it is illegal for a roofing contractor in Tennessee to pay, waive, or rebate your insurance deductible. Under Tenn. Code Ann. Section 62-6-604, offering to handle the deductible for a homeowner is a deceptive act. Reputable companies like Ultimate Solution Roofing & Exteriors will never offer to cover this cost. You should be cautious of any salesperson who suggests they can "waive" your deductible, as this could jeopardize your entire insurance claim.
What if the insurance check is made out to both me and my mortgage company?
It is standard practice for insurance carriers to include your mortgage lender as a payee on claim checks. Since the lender has a financial interest in the property, they must ensure the repairs are completed to protect their investment. You will need to send the check to your mortgage company's loss draft department for endorsement. Our team can provide the necessary documentation, such as the contract and final invoice, to help you manage this process.
Article by
Harry Stanley III
Harry Stanley III is a construction marketing strategist and fractional CMO at H&A Marketing. He has helped construction companies grow through website strategy, SEO, paid advertising, branding, lead generation, CRM systems, and professional content. His past work includes helping Meraki Solar generate an additional $3.7 million in revenue in his first year and supporting American Builders as a fractional CMO. Today, Harry works directly with custom home builders and construction companies to build marketing systems designed to generate qualified leads and measurable growth. https://harryandally.com